
We have been threated with defamation action or similar by the lawyer for Swoosh Finance, the money lender sponsor of the Capalaba Greyhound Racing Club that featured in a few stories last week about the inappropriateness of the club promoting it on their media.
This is our reply.
The lawyers name is Parker, and as they have not identified their pronoun we elected to refer to them as such.
————————————–
Dear Parker
To Whom It May Concern
https://www.peterprofit.com
Dear Sir,
The publisher does not identify as either a male or as the recipient of a knighthood.
We don’t like sexism.
In fact we resent it and regard it as reprehensible, as in our view it is a contributory factor to the struggles faced by people of non-male gender or gender identification in all spheres of life.
Dear Publisher is our suggestion for next time.
It is gender neutral, and less likely to cause harm or offence than ‘Sir’ when used as a greeting or salutation.
Re: Request to Remove Defamatory Content published on https://www.peterprofit.com – Swoosh Finance and Capalaba GreyHound Racing Club
There is none.
Swoosh Finance (Swoosh) is a proud sponsor of the Capalaba Greyhound Racing Club.
That’s the whole point.
We have been made aware of material published on peterprofit.com, namely three (3) articles which reference Swoosh Finance in a disparaging and defamatory manner.
Who made you aware?
Are you aware that it is a breach of our intellectual copyright for a non-paying subscriber to access or copy content published on the peterprofit.com website?
This term features prominently on the home page of the site, and with each published story. so you must have seen or read it.
Did you access the site yourself?
We would appreciate your answer to all three questions.
On the other note, yes we did reference Swoosh Finance disparagingly, but that was an honestly and very genuine held opinion as I hold payday lenders in extremely low regard, and have been consistent in our criticism of them and their industry over a long period of time.
However nothing that was written and published was defamatory Swoosh Finance, and we take umbrage at you asserting so.
Ausfinancial Pty Ltd trading as Swoosh Finance holds Australian Credit Licence 387993
Agreed.
No-one ever said you didn’t.
and is a responsible lender complying with the National Consumer Credit Protection Act 2009 and the National Credit Code.
That’s a matter to be determined, if necessary.
Additionally, Swoosh complies with the design and distribution obligations introduced on 5 September 2021, a Target Market Determination publicly available on the website which details the product, the market and its distribution.
Yes we read your Target Market Determination.
It confused us.
We are aware of the advertising requirements and code of ethics enacted by the Australian Communications and Media Authority (ACMA) which regulates communications and media content within Australia and the Australian Association of National Advertisers (AANA).
Pleased to hear that.
So are we.
We note you contend Capalaba Greyounds Racing Club has contravened the various advertising regulations and code of ethics.
This is incorrect.
We would tell you why, but are restrained from doing so by the fact that you Parker do not act for the Capalaba Greyounds Racing Club (sic) in this matter, or to the best of our knowledge based on the absence of disclosure to the contrary, on any matter at all.
By your own account your client is Swoosh Finance, your employer.
The interests of your client and the Capalaba Greyound (sic) club diverge.
A man cannot serve two masters.
A woman or a transgender or non-binary person can’t either.
We understand, summarily, that advertisements must not: target children; make exaggerated claims; be misleading; suggests gambling is a strategy for financial betterment and nor can it implicitly or explicitly be directed at vulnerable or disadvantaged groups (amongst others).
Agree.
We opine that the Swoosh Finance logo does not contravene the regulations or code of ethics.
Do you opine that the words Swoosh Finance, repeated twice on the semaphore board in one frame, might?
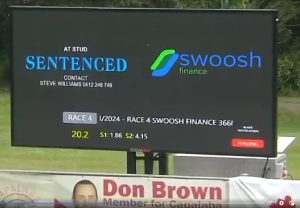
And who is your advertising directed at, if it’s not vulnerable or disadvantaged groups?
The type of people who would be so desperate that they would be willing to pay a $418 fee on a $2200 loan – equivalent to 19.0% fixed interest on the loan – to then allow your firm to charge them 47% per annum interest on the principal?
This means that the lender has to pay you an additional $1452 on a $2200 loan, meaning they have to pay $3652 back to clear their debt.
Who would agree to those conditions other than a vulnerable or disadvantaged person, acknowledging that potential problem gamblers fall into one or both of these categories?
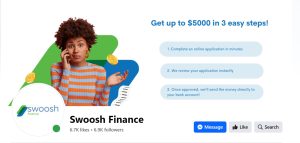
And what about the hyperlinks to Swoosh Finance that appear repeatedly on the Capalaba Greyounds Racing Club (sic) Facebook page?
https://www.facebook.com/profile/100063472393107/search/?q=swoosh
The ones that when you click on them take you straight to this below.
Are they okay too?
We opine that you are wrong.
As mentioned above, we assert the published material is defamatory in nature and in no particular order, we reference some of the following disparaging comments made:
“Swoosh don’t tell you who the comparison rate is made against. Break-leg Lenny the Loan Shark at the illegal casino is our guess”
Well all licensed financial services companies are bound by law to charge no more than 48% interest on loans, so who else could be charging the 66.0347% interest rate that you use as the comparator in the our payday loans rates and fees disclosure on your website, other than Lenny The Shark?
A licensed lender would be breaking the law if they were doing so, and surely you would have shared any knowledge you may have of such unlawful practices with the regulator.
“There is no responsible gambling message on the Capalaba semaphore board, which is an electronic medium advertising the high interest payday lender Swoosh Finance”
This is a fact.
What’s the problem?
“…for a third tier lender who can instantly approve their application for loan and put it in their account immediately via Pay ID”
This is a fact.
You are a third-tier lender, as defined.
You can and do instantly approve a loan when the required documents have been received, which can be instantly if the applicant has the documents to hand.
You do put the cash into the borrower’s account immediately via Pay ID.
You advertise it to the public at large.
So what is the issue?
No entiendo.
We don’t understand.
“Promoting an instant access payday loan service to gamblers”
This is a fact.
“Swoosh Finance is a third-tier money lender that provides short term loans at exorbitant thought just legal interest rates”
This is a fact.
“…is accepting sponsorship from a pay-day lender to advertise their usurious wares, that being short-term loans at 47% interest to problem gamblers with bad credit rating, secured over their cars which will be repossessed if they can’t pay”
This is provable.
“Are they going to put Swoosh easy credit fast loan ATM’s at their dog track so that punters can top up their banks at 47% interest after they knock off their own?”
This is a rhetorical question, a literary device used by writers since antiquity.
The question answers itself.
We consider that this content which identifies Swoosh Finance, goes further than an honest opinion, is without factual basis and is highly defamatory.
We disagree.
Vehemently.
We seek that you immediately withdraw the three (3) articles containing this material by close of business today, Friday 22 March 2024, failing which we shall consider our next steps regarding a claim being brought for reputational damage given we contend the criteria for the same has been met.
Polite answer, no.
Good luck, for we reckon you’re backing a loser.
Please consider this a first and final request to remove the published material.
If we do, will you promise to stop wasting our time with your unfounded claims?
Cheers
peterprofit.com